The short answer
How does rent-to-own work in Wilmington, NC?
Rent-to-own lets you rent a home now with an agreed option to buy it later, so you have time to save and get ready to buy while you live there. Jonathan Swanson, a licensed North Carolina real estate broker (License #231105-NC, Sea Gate Realty, Inc.) helps renters around Wilmington, Leland, Hampstead and Jacksonville explore rent-to-own and owner-financing homes — not everyone will qualify, and every agreement is different. Let’s talk: call or text (910) 367-5722; the conversation is free.
Your Local Wilmington Real Estate Partner
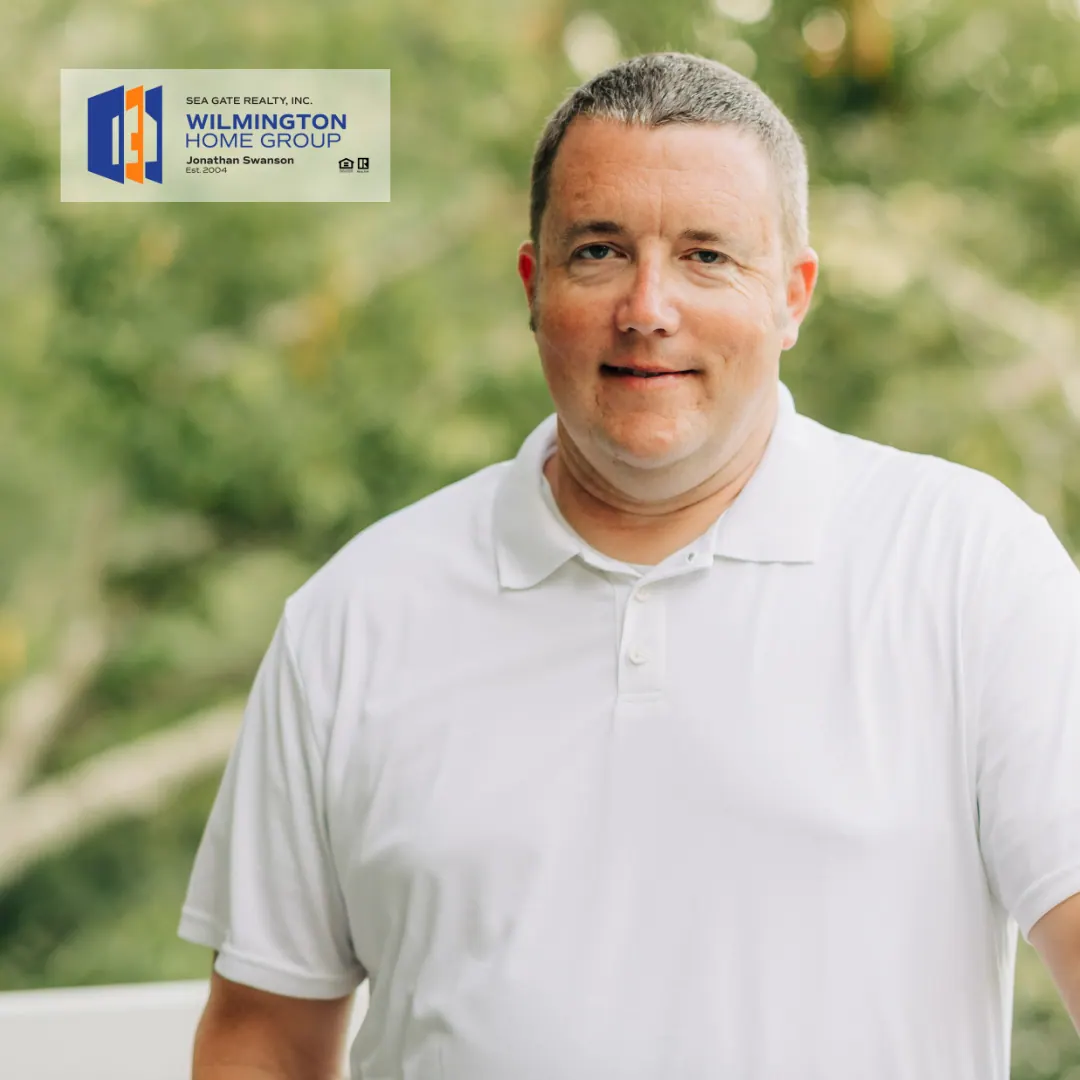
Hello, I’m Jonathan!
I’ve lived in Wilmington since 1995 and began investing in real estate in 2004 after leaving the corporate world.
I’ve also served on the board of the Coastal Carolina Real Estate Investment Association to support local investors and promote real estate education.
As a broker with Sea Gate Realty, Inc., I help people find a realistic path to owning a home — through rent-to-own or owner financing — and I’m honest when it isn’t the right fit yet.
Here’s How I Can Help…
Help You Explore Your Options
Are you unsure about buying a Wilmington home right now? Or you just want to live in a home first and think about it later. Don’t worry. I’ll help you understand the options you have right now.
Connect You with Affordable Homes
Finding a home that fits your budget can be hard. So, let me help you. I focus on homes in Wilmington that offer flexible ways to move in without a big upfront payment.
Simplify the Paperwork and the Process
Moving to a new house or converting it to a Rent-to-Own requires a lot of real estate papers. And it can get confusing! If you need a little assistance, I can help you manage them.
Offer Ongoing, No-Pressure Support
Just need someone to talk to about your home? I’m willing to share my expertise with you. Even after you move in, I’m here to answer your questions and help you take the next steps.
Are you ready to rent-to-own a house?
It’s OK to Message Us!
Why Is Rent-to-Own a Good Idea?
Rent-to-own can be a way to move into a home without needing a full mortgage right away. You rent and live in the house while preparing to buy it later, giving you time to save and prepare to buy. (For credit questions, a HUD-approved housing counselor can help.) It also benefits sellers who get steady rent and a good chance to sell to someone who cares for the home. Here’s a deeper look:
For Buyers
It makes getting into a home easier because you don’t need a full mortgage upfront. You get time to save and prepare while living in the house.
For Sellers
You get steady rental income and someone who cares for your home. It can also mean a sale later, since the renter plans to buy.
For Both
Rent-to-own lowers moving hassle because buyers live in the home while preparing to own it, and sellers avoid empty properties with no income.
Bottomline: Rent-to-own offers a flexible way to move toward homeownership by living in the home while saving and preparing to buy, making it easier for buyers to get started and giving sellers steady income with fewer risks.
Frequently Asked Questions on Rent to Own
What if I want to rent now but am unsure about buying?
Rent-to-own gives you the chance to try living in the home first without rushing into buying. As a buyer, this helps you make a confident decision about ownership after experiencing the home and neighborhood.
For sellers, it means having a tenant who intends to buy, which can reduce vacancy risks.
How does my rent payment turn into part of the home purchase?
In some agreements, part of each rent payment is credited toward a future down payment — it depends entirely on the written agreement, so have a real estate attorney review it. This helps buyers save gradually while living in the home, making it easier to afford purchase costs.
Sellers gain steady rental income with the potential of a future sale, offering financial stability and commitment from the tenant.
What if I decide not to buy after renting?
Buyers usually have the option to walk away, but they risk losing any rent credits or upfront fees paid.
For sellers, this means they keep the option fee but regain control to find another buyer or renter, so it’s important both sides understand the terms to avoid surprises.
Who is responsible for repairs and maintenance during the rental period?
Responsibilities vary by contract. Buyers often handle minor repairs and day-to-day upkeep since they’re preparing for ownership.
Sellers usually take care of major repairs like structural issues. Clear agreements help both parties avoid disputes about who handles what costs.
Can I make improvements to the home while renting?
Buyers might want to make changes or upgrades, but they should always get the seller’s approval first. While improvements could increase the home’s value, buyers might not be compensated if they don’t complete the purchase, so discussing this beforehand is key.
What happens if the buyer can’t get a mortgage when it’s time to buy?
If financing falls through, buyers may lose their option to purchase and any credits paid.
Sellers then can look for other buyers or renters. This risk encourages buyers to improve credit and finances during the rental period to increase their chances of mortgage approval.
How long do these agreements usually last, and what happens afterward?
Typical agreements last 1 to 3 years, giving buyers time to prepare financially and emotionally. At the end, buyers decide whether to complete the purchase or walk away. Sellers get paid rent in the meantime and have a potential sale lined up, but if the buyer opts out, the property is available again.
Read About Selling and Buying Homes in Wilmington
You might find these helpful on your journey:
- 3 Steps To Selling Your Property Via A Rent To Own Agreement In Wilmington
- How You Can Find Free Rent to Own Home Listings in Wilmington
- How Do Rent To Own Homes Work In Wilmington?
More Resources About Rent-to-Own
- North Carolina Housing Finance Agency — How to Rent to Own
- University of California Berkeley Terner Center — Lease-Purchase Homeownership Models
- North Carolina Department of Justice — Rent-to-Own Consumer Protection
Connect With Us
Feel free to reach out with questions or just to talk about your options. Whether buying or selling, there are ways to make it all easier and less stressful.
You can fill up the form below or contact us at (910) 367-5722.
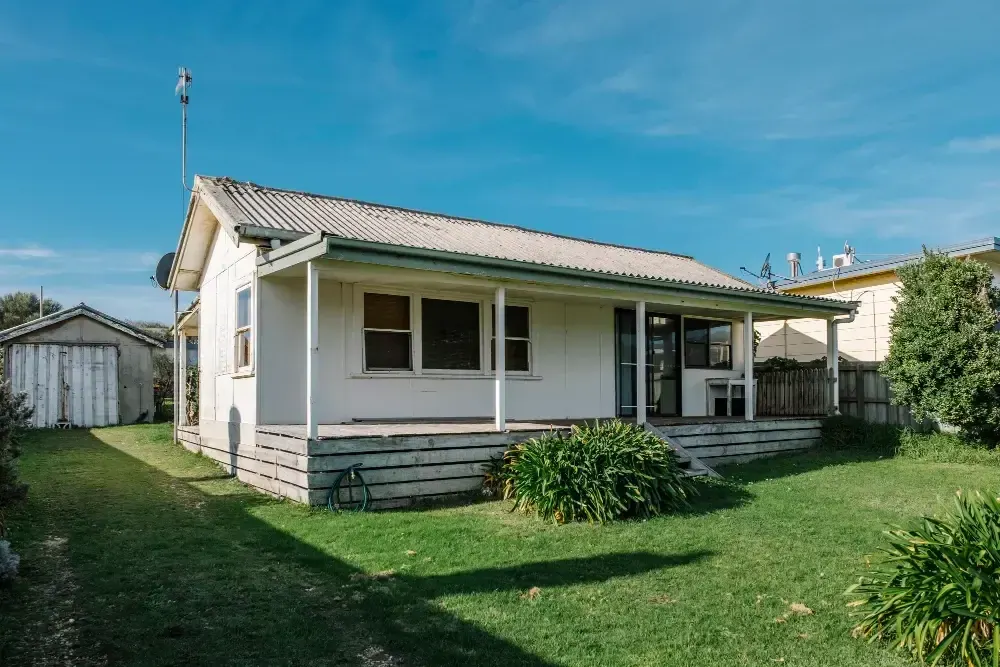
Rent to own in the Wilmington area
A path to owning a home: rent-to-own or owner financing
If a traditional mortgage isn’t a fit right now, rent-to-own or owner financing can be a path to owning a home in Wilmington, Leland, Hampstead, Jacksonville and nearby towns. We start by listening to what you’re looking for. Not everyone will qualify, and nothing is guaranteed — but a conversation is free.
How rent-to-own commonly works
In a typical rent-to-own (lease-option or lease-purchase) arrangement, you rent the home for a set period with an agreed option to buy it later. Many agreements include upfront option money, and the price, the length of the lease and who handles maintenance are written into the agreement. Every agreement is different, so please read it carefully and have a real estate attorney review it before you sign.
How owner financing differs
With owner (seller) financing, you buy the home now and make monthly payments to the seller instead of a bank, on terms agreed up front. The deed, the note and the payment terms are handled by a closing attorney. It can be a fit when you have a down payment and steady income but don’t fit a bank’s box today.
Who it tends to fit
We generally look for average credit or better — slightly below average may still work when the rest of the application is strong (down payment, steady work, good references). The same standards apply to everyone. Steady income, some money set aside for a down payment or option money, and good rental references matter most. Applications are reviewed the same way for everyone, in line with the Fair Housing Act.
Free help, even if this isn’t the right fit
If rent-to-own isn’t right for you today, we’ll still try to point you in a good direction — for example a HUD-approved housing counselor for budgeting or credit questions, or a local lender. We don’t give credit, legal or financial advice. We’re not attorneys or CPAs, but we know good local ones and are happy to connect you with a trusted attorney, CPA or other professional if you need one.
Questions many renters ask about rent to own
Do I need perfect credit for rent to own?
No. We generally look for average credit or better — slightly below average may still work when the rest of the application is strong (down payment, steady work, good references). The same standards apply to everyone.
Does filling out the form pull my credit?
No. The short form asks you to describe your situation in ranges. We don’t ask for a Social Security number and we don’t pull credit.
Is a home guaranteed if I qualify?
No. Not everyone will qualify, and sending the form doesn’t guarantee a home, approval or any particular terms. It starts a conversation with Jonathan or his assistant.
What is option money?
In many rent-to-own agreements, option money is an upfront payment for the right to buy the home later. How it’s handled depends on the written agreement, so please have a real estate attorney review any agreement before you sign.
Can you help me fix my credit?
We don’t give credit or financial advice. A HUD-approved housing counselor (HUD’s line is 800-569-4287) can help, often at little or no cost.
Is rent to own the same as owner financing?
No. With rent to own you rent the home first and have the option to buy it later; with owner financing you buy the home now and make monthly payments to the seller instead of a bank. Both are put in writing, and a closing attorney handles the deed and paperwork.
How much money do I need upfront for rent to own?
It varies by home and agreement. Many rent-to-own agreements include upfront option money plus the first month’s rent and a deposit. We’ll go over the numbers for a specific home before you commit, and a real estate attorney should review any agreement before you sign.
Are there rent-to-own homes available in Wilmington right now?
Available homes change often, so the best way to know is to tell us the area, size and budget you’re looking for. Jonathan will let you know honestly what might fit — or whether another path, like working with a local lender, makes more sense.
Which areas do you offer rent to own in?
Mostly Wilmington and nearby towns such as Leland, Hampstead, Castle Hayne, Burgaw and Jacksonville, across New Hanover, Brunswick, Pender and Onslow counties.
Let’s talk
A real, local person picks up.
You'll usually reach Jonathan or his assistant — not a call center. Call, text, chat, or email, whatever's easiest for you. Jonathan is happy to set up a phone call or a visit at your place, your choice. No pressure — just answers so you can make the best decision.
When you can reach us: Jonathan is available live by phone or text 9 am–9 pm Eastern, 7 days a week — and often outside those hours if you need help. Forms and chat take messages 24/7, and we’ll respond as soon as possible.
Locally owned & serving Wilmington since 2004 · (910) 367-5722 · [email protected]